OKLA RISK ADVISORS 913-717-9128Request service

Large Loss and Catastrophe Claims Adjusting

A large loss adjuster and independent adjuster team for commercial property claims, condo association claims, and hurricane and hail claims. Led by an Executive General Adjuster, nationwide.

Executive General Adjuster25+ years catastropheLarge loss commercial

Built for carriers, MGAs, TPAs and IA firms. Senior review on every file, led by an adjuster ranked in the top 5 percent for file quality, cycle time and customer service.
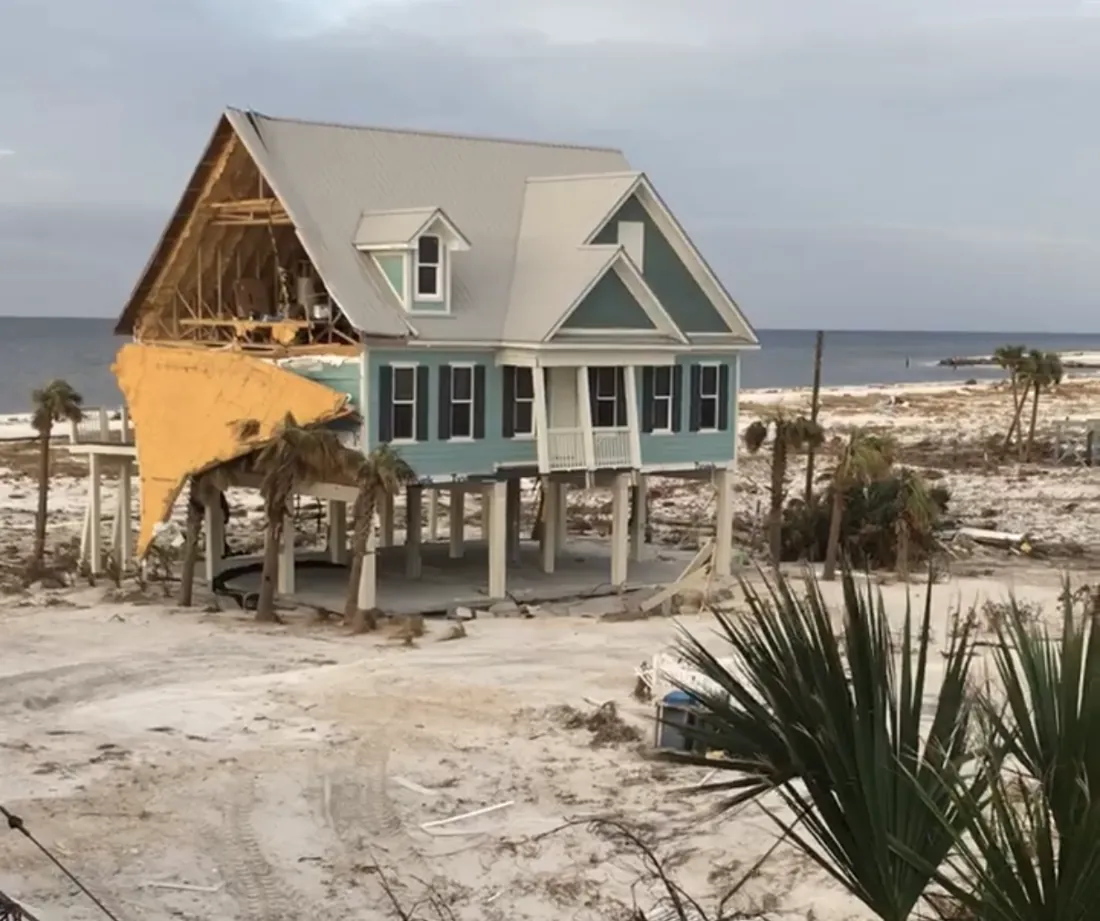
Elevated beach house with roof and wall sheathing torn away after a hurricane
Field inspection: an elevated coastal home after a hurricane.
Who we serve
  • National and regional carriers
  • MGAs and program administrators
  • Third-party administrators
  • Independent adjusting firms
  • Self insured entities and pools
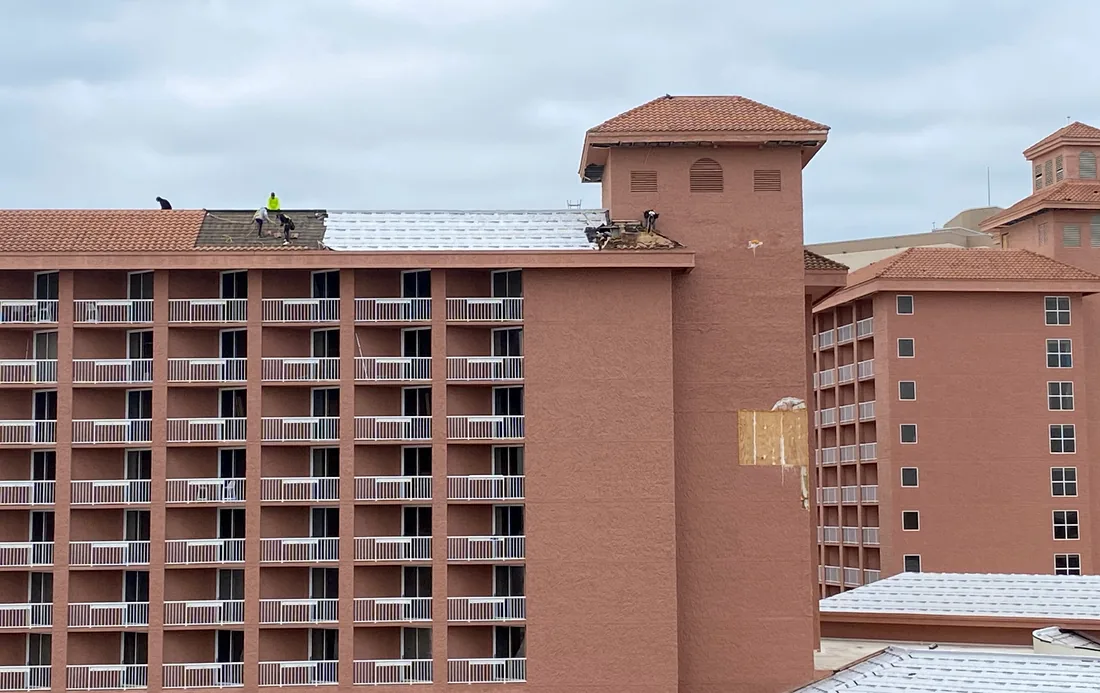
Crews replacing hurricane-damaged tile roofs across a high-rise commercial complex, with plywood covering wall damage
Large commercial loss: roof replacement underway across a high-rise complex after a hurricane.
Why clients call

What brings carriers, TPAs and IA firms here

Large loss

A commercial or condo loss nobody wants

General adjuster authority on complex commercial buildings, associations and multi-building complexes.

Large loss work
Surge

We need adjusters under our brand

Overflow and catastrophe capacity working in your systems and under your program.

Adjuster staffing
File quality

We need a book of files reviewed

Estimate review, reinspection and closed file audits, with a written findings report.

Claim review and QA
Operations

Cycle times and severity are slipping

Cycle time, leakage and vendor panel review, with ranked recommendations.

Operations consulting
Flood

We need an NFIP certified adjuster

Certified at all four NFIP levels, including RCBAP and commercial.

NFIP flood claims
Services

What the claims practice delivers

Xactimate estimating, multi-state licensing and work done to your guidelines.

01

Large loss and commercial claims

Commercial buildings, condominium and homeowner associations, and multi-building complexes, handled end to end. Coverage analysis, business interruption and settlement negotiation at general adjuster authority.

Commercial propertyCondo and HOABusiness interruption
02

Catastrophe field adjusting

Field adjusting on hurricane claims, hail claims, and wind, tornado, wildfire and flood events nationwide. Scales from single assignments to multi-adjuster teams, with quality control on every file.

CAT deploymentDaily assignmentsSurge
03

Desk adjusting and file management

Remote desk adjusting, virtual inspection review and file management to your standards, from first notice of loss to closeout.

Desk adjustingVirtual inspectionFNOL to closeout
04

Subcontract and white label capacity

Licensed field and desk adjusters working through your firm, in your systems and under your brand, with senior review on every deployment.

IA firm subcontractingTPA supportWhite label
05

Claim review and quality assurance

Estimate review, reinspection, closed file audit and reserve review as standalone work. The firm does not need to have handled the file.

Estimate reviewReinspectionFile audit
06

Claims operations consulting

Cycle time, leakage, guidelines, QA program design, vendor panels and catastrophe planning. You get a findings report a claims executive can act on.

Cycle timeLeakageVendor panel
07

NFIP flood claims

Certified at every NFIP level: RCBAP, commercial, homeowners and mobile home. Write Your Own assignments handled to NFIP standards.

RCBAPCommercial floodWYO carriers
Track record

Representative catastrophe and large loss work

  • Large loss and commercialCondominium associations, multi-building complexes, retail, office, industrial and habitational buildings, including business interruption.
  • Catastrophe responseHurricane, tornado, hail, wildfire, flood and freeze events nationwide since 2004.
  • VolumeThousands of residential and hundreds of commercial claims for carriers, TPAs and IA firms.
  • Largest engagementA Gulf Coast high-rise condominium complex with about $85 million in estimated damage.
Performance record
File qualityTop 5%
Cycle timeTop 5%
Customer serviceTop 5%
Claims handledThousands since 2001
DeploymentsMajor US catastrophes since 2004

References are furnished on request.

How a file moves

First notice of loss to closeout

Every file follows the same steps, so it holds up at audit.

Step 1

Assignment and FNOL

Intake under client guidelines, coverage confirmation, and contact within service level windows.

Step 2

Inspection

Field or virtual inspection, damage documentation, measurements, and photo record.

Step 3

Scope and estimate

Scope of loss, causation analysis, and Xactimate estimate to client standards.

Step 4

Settlement

Coverage application, negotiation, and reserve reporting through resolution.

Step 5

Closeout

Audit ready file, supplements as warranted, and clean closeout documentation.
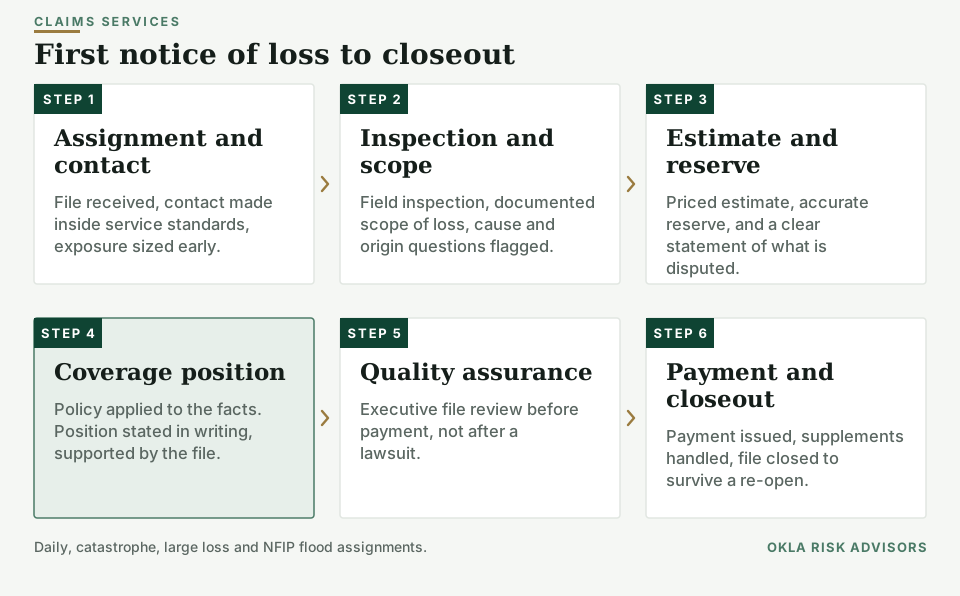
Six step diagram of the catastrophe claims lifecycle: assignment and contact, inspection and scope, estimate and reserve, coverage position, executive quality assurance review, and payment and closeout.
Executive quality review happens before payment, not after a dispute starts.
How we work

Executive-led, not a volume shop

  • Defensible filesScope, causation and value documented to hold up at audit.
  • Your program, your standardsWork done in your systems and to your guidelines, under your brand if needed.
  • Carrier-side judgmentTen years as a claims supervisor and special commercial adjuster at Farmers Insurance and Zurich.
Claims credentials
DesignationExecutive General Adjuster
Experience25+ years P&C catastrophe and large loss
PerformanceTop 5%: quality, cycle time, service
Home stateTexas DHS license 3509355
Other statesAL, AR, LA, MS, NM, OK; reciprocal with TX
NetworkAdjuster licensed in every licensing state
NFIPRCBAP, commercial, homeowners, mobile home
RestorationIICRC WRT and ASD
EstimatingXactimate, Cotality Estimate
NPN5700272
For claims and vendor managers

Placing work: common questions

What claim types and sizes do you handle?

Daily residential assignments through large commercial and condominium losses. Complex files are directed by a senior Executive General Adjuster.

Can you work under our firm instead of directly for the carrier?

Yes. The firm can work as a subcontractor to IA firms, TPAs and program managers, under your brand and program.

Do you review files you did not handle?

Yes. Estimate review, reinspection, closed file audit and reserve review are standalone services.

What does operations consulting cover?

Cycle time, leakage, reserves, guidelines, QA program design, vendor panels and catastrophe planning, delivered as a written findings report.

Are you NFIP certified?

Yes, at all four levels: RCBAP, commercial, homeowners and mobile home.

Have a loss or a book of files to look at?

Tell us what you need and who would do the work.